How to Build Wealth Through Rental Properties: The Long-Game Strategy Guide
How to Build Wealth Through Rental Properties: The Long-Game Strategy Guide
By Michael Glaspie | The Real Estate CFO | G2 Business Solutions
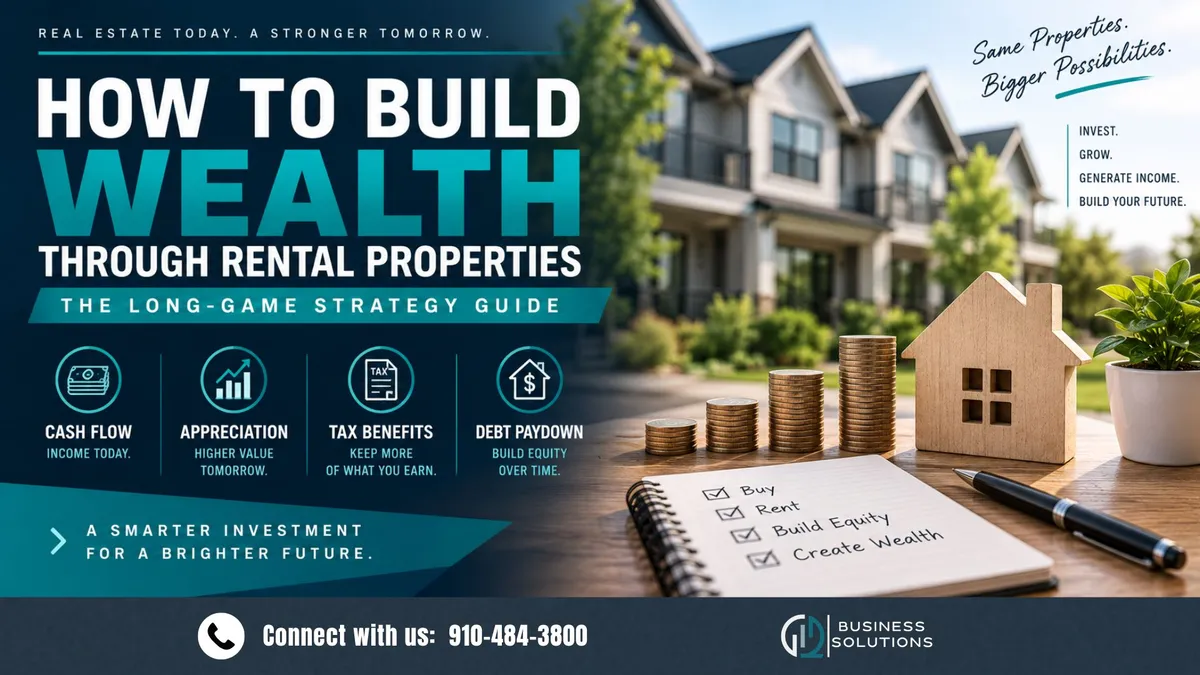
Rental property investing isn't the flashiest strategy in real estate. There's no dramatic flip reveal, no rapid-fire wholesale deal, no viral moment. What there is: consistent, compounding, four-dimensional wealth creation that holds up over decades.
No other commonly accessible asset class builds wealth in four ways simultaneously — cash flow, appreciation, tax benefits, and debt paydown. Understanding how these four pillars work together is the foundation of every successful buy-and-hold portfolio.
This guide is your complete roadmap to building wealth through rental properties — from your first deal to a fully optimized portfolio.
1. The Four Ways Rental Properties Build Wealth
Cash Flow
The monthly income your property generates after all expenses — mortgage, taxes, insurance, management, maintenance, and vacancy allowance. Cash flow is the fuel that funds your lifestyle and your next investment.
Appreciation
Over time, real estate generally increases in value. Long-term appreciation (3–4% annually on average nationally) compounds significantly over a 10, 20, or 30-year hold period. A $200,000 property at 3% average annual appreciation is worth $370,000 in 20 years — and $484,000 in 30.
Tax Benefits
Depreciation, mortgage interest deductions, repair deductions, and professional service deductions create significant tax advantages that effectively increase your real return on investment. These benefits are unique to real estate and unavailable to most other investment types.
Debt Paydown
Every mortgage payment your tenant makes on your behalf increases your equity. On a 30-year mortgage, you're building equity slowly at first and accelerating as the loan matures. This equity becomes a tool for future acquisitions or an asset you own free and clear.
2. Getting Started: What You Actually Need
The biggest lie told to aspiring real estate investors is that you need a lot of money to get started. It helps — but it's not the prerequisite most people think it is.
What You Actually Need
• Enough for a down payment (3.5–5% for house hacking with FHA; 15–25% for traditional investment property loans)
• Reserves for unexpected expenses (3–6 months of carrying costs, minimum)
• Basic financial literacy — understanding cash flow, cap rates, and debt service
• A reliable team: real estate agent, lender, inspector, and CPA
• Patience and a long-term mindset
House hacking — buying a multi-unit property, living in one unit, and renting out the others — is the most accessible entry point for most investors. It allows you to use owner-occupied financing rates (3.5–5% down) while immediately generating rental income.
3. How to Analyze a Rental Property Deal
Every deal starts with the numbers. Here's a simple framework for evaluating a rental property:
Step 1: Calculate Gross Rental Income
Research market rents for comparable units. Be conservative — don't assume the highest comp in the market.
Step 2: Apply a Vacancy Allowance
Assume 5–10% vacancy (even if the current owner claims 100% occupancy). Things change.
Step 3: Calculate Operating Expenses
Estimate: property taxes, insurance, maintenance (budget 1% of property value/year), property management (8–12% of rents if applicable), and capital expenditures reserve.
Step 4: Calculate Net Operating Income (NOI)
NOI = Gross Rent - Vacancy - Operating Expenses. Do not include mortgage payment in NOI.
Step 5: Determine Cash Flow
Cash Flow = NOI - Annual Debt Service. If it's positive, you have a cash-flowing deal.
Step 6: Calculate Key Ratios
• Cap Rate = NOI ÷ Purchase Price (compare to market cap rates)
• Cash-on-Cash Return = Annual Cash Flow ÷ Total Cash Invested
• Gross Rent Multiplier = Purchase Price ÷ Annual Gross Rent
4. Financing Your Rental Portfolio
Your financing strategy evolves as your portfolio grows. Here's how most investors progress:
First 1–4 Properties: Conventional Loans
Fannie Mae and Freddie Mac allow conventional financing on up to 10 properties for qualifying borrowers. Rates are favorable. Requirements: good credit, documented income, and 15–25% down on investment properties.
Growing Portfolio: Portfolio Loans
Once you hit the conventional loan limit, portfolio lenders (often local banks and credit unions) offer loans outside of agency guidelines. Terms are less standardized but more flexible.
DSCR Loans
Debt Service Coverage Ratio loans qualify based on the property's income rather than your personal income. Ideal for investors with complex income situations or large portfolios.
Creative Financing (for the right deal)
Subject-to, seller financing, and private money fill gaps that conventional lenders can't. See our Creative Financing Guide for a full breakdown.
5. Property Management: Self-Manage vs. Hire
This is one of the most personal decisions in rental investing. There's no universally right answer.
Self-Management
• Saves 8–12% of monthly rents
• Requires time, availability, and systems
• Works best for local investors with small portfolios
• Becomes difficult to scale beyond 5–10 units without significant operational infrastructure
Professional Property Management
• Costs 8–12% of monthly rents plus leasing fees
• Frees your time completely
• Quality varies widely — vet carefully and review monthly financial statements
• Essential for out-of-state investing
Many investors self-manage early to learn the business, then transition to professional management as they scale. The key is treating the management fee as a real operating expense when analyzing deals — not something you'll eliminate by doing it yourself.
6. Tax Benefits Every Rental Investor Should Know
• Depreciation: Deduct the cost of your structure over 27.5 years — a non-cash deduction that reduces taxable income without spending money
• Mortgage interest: Deductible in full for investment properties
• Repairs and maintenance: Deductible in the year incurred
• Professional services: CPA, attorney, property manager fees are all deductible
• Property taxes: Fully deductible as a business expense
• Insurance: Deductible in full
• Travel: Miles driven to and from your properties are deductible
These deductions can create a situation where a profitable rental property shows a paper loss for tax purposes — meaning you collect rent, build equity, and pay little to no tax on that income. This is a legal and intentional feature of real estate investing.
7. Scaling Your Rental Portfolio
Scaling from 1 property to 5 to 20+ is a systems game. Here's how serious investors do it:
• Recycled capital: BRRRR strategy, cash-out refinances, and 1031 exchanges keep capital working rather than sitting
• Relationships: Build a network of agents, lenders, and contractors who bring you deals and solve problems quickly
• Systems: Standardize rent collection, maintenance response, and financial reporting so you're not reinventing the wheel with each new property
• Team: A bookkeeper, CPA, and property manager working in coordination make scaling operationally sustainable
• Patience: Most large portfolios were built over 10–20 years, one intentional deal at a time
8. Common Mistakes That Stall Portfolios
• Underestimating expenses and overestimating rent — the classic pro forma lie
• Ignoring reserves — one big repair can wipe out a year of cash flow
• Buying in the wrong market because it's local and familiar
• Over-leveraging in a rising rate environment
• Failing to track financials by property — you can't manage what you don't measure
• Waiting for the perfect deal and never starting
9. Frequently Asked Questions
Q: How many rental properties do I need to replace my income?
A: It depends on your monthly expenses and the cash flow per property. If each property generates $400/month in net cash flow and you need $4,000/month, you need 10 properties. The more you optimize each deal, the fewer you need.
Q: Is it better to buy cheap properties for cash flow or expensive properties for appreciation?
A: This is a false binary. The best markets offer a balance of both. Generally, lower-priced markets (Class B/C) offer stronger cash flow; higher-priced markets (Class A) offer stronger appreciation. Match your strategy to your goals.
Q: When should I consider selling a rental property?
A: Consider selling when: ROE has dropped significantly due to appreciation, the market has peaked and you can 1031 into a better opportunity, the property has chronic maintenance issues, or the local market fundamentals have deteriorated.
10. Final Thoughts
Building wealth through rental properties is not complicated. It's not fast. And it's not particularly exciting on a day-to-day basis. But it is reliable, proven, and available to nearly any investor willing to learn the fundamentals and play the long game.
The investors who succeed aren't necessarily the smartest in the room. They're the most consistent. They buy good deals, manage them well, track their finances, optimize their taxes, and keep building.
Start with one. Do it right. Then do it again.
About the Author
Michael Glaspie is a former U.S. Army Green Beret, real estate investor (134+ rental units), and Fractional CFO to real estate investors nationwide through G2 Business Solutions. He helps investors increase profits, reduce taxes, and build wealth through strategic financial management.
YouTube: @themichaelglaspie | Instagram: @michael.s.glaspie | G2BusinessSolutions.com