Creative Financing in Real Estate: How to Buy Properties Without a Traditional Bank Loan
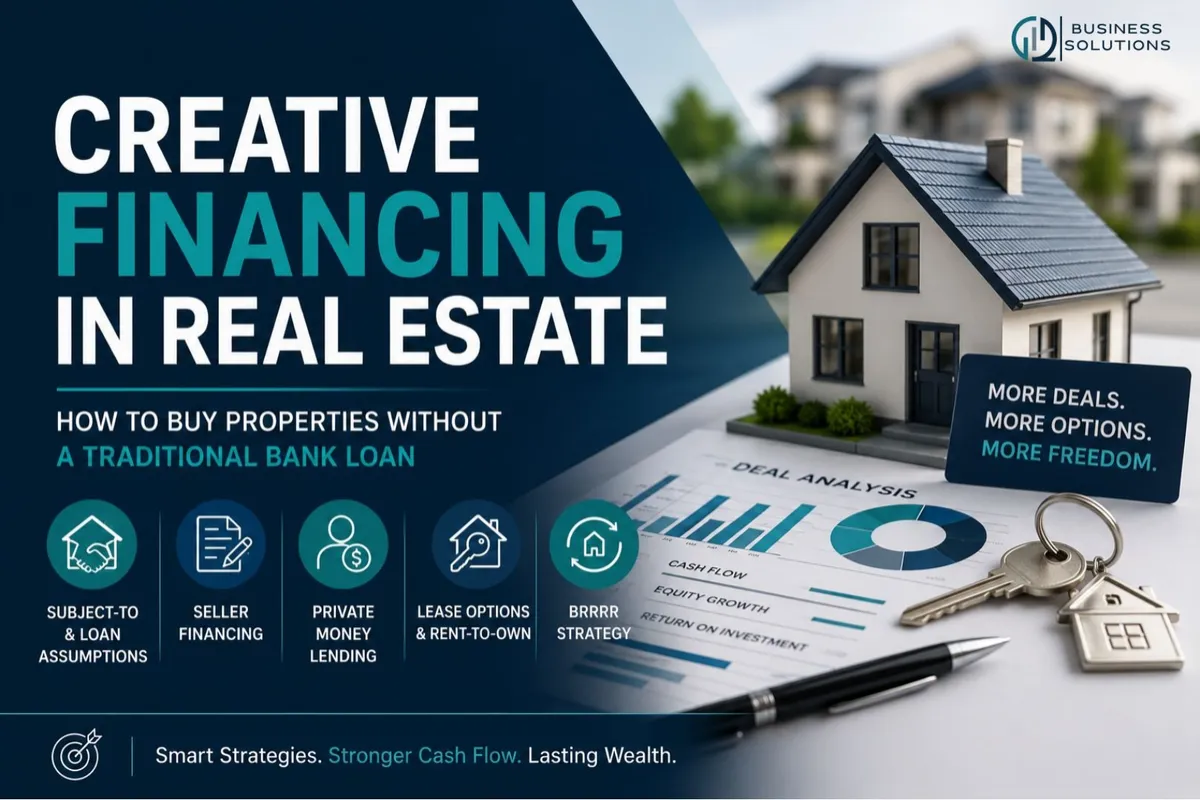
Creative Financing in Real Estate: How to Buy Properties Without a Traditional Bank Loan
By Michael Glaspie | The Real Estate CFO | G2 Business Solutions
Most people think you need perfect credit, a 20% down payment, and a friendly bank to buy real estate. That's the conventional path — and it works. But it's not the only path.
Creative financing strategies allow investors to acquire properties using little to no traditional bank financing. These aren't loopholes or gray areas — they're legitimate, time-tested real estate strategies used by sophisticated investors every day, especially when interest rates are high or credit is limited.
This guide covers the most powerful creative financing tools available to real estate investors, how they work, and when to use each one.
1. Why Creative Financing Matters
In a high-interest-rate environment, conventional financing can turn what looks like a good deal into a cash-flow negative investment. Creative financing lets you work around high rates by accessing existing financing at better terms — or eliminating the bank entirely.
Beyond rates, creative financing opens the door for investors who:
• Don't yet qualify for conventional loans
• Have capital tied up in other investments
• Want to close deals faster without bank approval timelines
• Are targeting sellers who need flexibility, not just a high price
2. Subject-To: Taking Over Existing Mortgages
A subject-to (or 'sub-to') deal means you purchase the property and take over the seller's existing mortgage — without formally assuming the loan or getting new financing. The mortgage stays in the seller's name; you make the payments.
How It Works
You negotiate directly with the seller. If they have a 3.5% mortgage from 2021 and you can take over those payments, you get access to that rate in a 7% market. The seller is relieved of the property (often because they need to sell quickly due to hardship, relocation, or financial pressure).
The Key Risk: Due-on-Sale Clause
Most mortgages include a due-on-sale clause that technically allows the lender to demand full repayment if ownership transfers. In practice, lenders rarely enforce this when payments are being made consistently. That said, this is a risk to understand and manage with proper legal counsel.
When Subject-To Makes Sense
• Seller has a low-rate existing mortgage
• Seller needs to sell fast and isn't focused on maximizing price
• Current interest rates make new financing expensive
• You have the cash flow to make the existing payments
3. Seller Financing: The Seller Becomes the Bank
In a seller-financed deal, the seller of the property acts as the lender. Instead of getting a bank loan, you make monthly payments directly to the seller, with interest, according to terms you negotiate together.
How It Works
You agree on a purchase price, down payment (if any), interest rate, and repayment term. A promissory note and mortgage (or deed of trust) are drawn up. The seller receives monthly payments, often at a rate better than what they'd earn in a savings account, and you get the property without bank approval.
Benefits for Both Parties
• Seller: generates ongoing income, avoids large capital gains event, and potentially earns higher interest than other investments
• Buyer: no bank approval required, more flexible terms, potentially faster closing, and potentially below-market interest rates
Common Terms
Seller financing terms vary widely. Common structures include 5–10 year terms with a balloon payment, interest-only payments, or fully amortizing loans. Everything is negotiable — that's the beauty of this strategy.
4. Loan Assumptions: Inheriting Favorable Terms
Some loans are assumable — meaning the buyer can take over the seller's loan at its current balance and interest rate. FHA and VA loans are the most common assumable loan types.
In a high-rate market, assuming a 2021 FHA loan at 3.25% instead of getting new financing at 7% is a massive financial advantage. The gap between the loan balance and purchase price is typically paid in cash or through secondary financing.
Loan assumptions require lender approval, unlike subject-to, and the original borrower is typically released from liability once the assumption is complete.
5. Private Money Lending
Private money lenders are individuals (not banks) who lend capital secured by real estate. They might be:
• High-net-worth individuals looking for better returns than traditional investments
• Other investors who've built capital and want to deploy it passively
• Friends, family, or business connections
Private money is typically faster, more flexible, and less documentation-heavy than bank financing. Interest rates are usually higher (8–12% is common) but the trade-off in speed and flexibility is often worth it for the right deal.
6. Lease Options and Rent-to-Own
A lease option gives you the right (but not the obligation) to purchase a property at a predetermined price within a specified time period. You pay option money upfront and rent during the lease term, with a portion often applied toward the purchase price.
This strategy works well when:
• You need time to improve your credit or save a down payment
• You believe the property will appreciate and want to lock in today's price
• The seller is open to creative solutions and not in a rush for a full cash-out
7. BRRRR and Refinancing Strategies
BRRRR (Buy, Rehab, Rent, Refinance, Repeat) isn't purely creative financing — but the refinance step is how many investors recycle their capital to fund the next deal without using new money.
By forcing equity through renovation, you can often pull out most or all of your original investment in a cash-out refinance, then repeat the process. This is one of the most powerful portfolio-scaling strategies available.
8. The Financial Side of Creative Deals
Creative financing is exciting — but it still requires rigorous financial analysis. Before closing any creative deal, you need to know:
• What are the total monthly carrying costs? (Existing mortgage payment + taxes + insurance + maintenance)
• What is the actual cash flow after all expenses?
• What is your exit strategy if the deal doesn't perform as expected?
• What are the tax implications? (Some creative structures have unique tax treatment)
• How does this deal fit into your overall portfolio strategy and cash flow picture?
9. Frequently Asked Questions
Q: Is subject-to legal?
A: Yes, subject-to is legal. The due-on-sale clause in most mortgages is rarely enforced when payments are made on time, but it is a risk to understand. Work with a real estate attorney experienced in creative financing.
Q: How do I find sellers open to seller financing?
A: Sellers who own their property free and clear (no mortgage) are the best candidates — they have no lender to satisfy. Expired listings, absentee owners, and sellers in pre-foreclosure are also common targets for creative financing discussions.
Q: What's the biggest mistake investors make with creative financing?
A: Getting excited about the structure and ignoring the numbers. A creative deal with negative cash flow is still a bad deal. Run the financials first.
10. Final Thoughts
Creative financing expands your options. It lets you acquire properties in markets and conditions where conventional financing doesn't work, and it creates win-win scenarios for both buyer and seller.
But like all tools, it works best when you understand it fully and apply it strategically. Learn the strategies, run the numbers, build the legal documentation, and use these tools to grow your portfolio in any market.
About the Author
Michael Glaspie is a former U.S. Army Green Beret, real estate investor (134+ rental units), and Fractional CFO to real estate investors nationwide through G2 Business Solutions. He helps investors increase profits, reduce taxes, and build wealth through strategic financial management.
YouTube: @themichaelglaspie | Instagram: @michael.s.glaspie | G2BusinessSolutions.com